Borderless.xyz Builds Stablecoin Payment Coverage Across 113 Countries
Kevin Lehtiniitty says Borderless.xyz is expanding local payment access while tackling compliance delays and gaps between promised and live services.
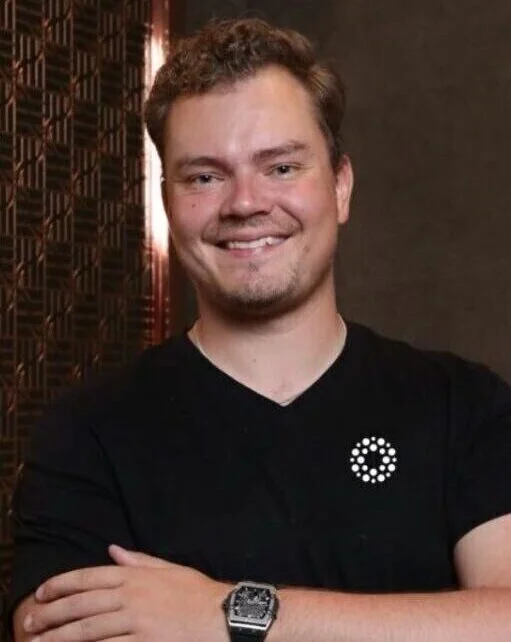
Stablecoins can settle in seconds, but that speed can disappear when funds need to reach a local bank account or wallet. Borderless.xyz is building around that last step: it connects payment companies to local providers that convert stablecoins into local currency and deliver funds over domestic payment rails. Its network now reaches 113 countries, according to CEO and founder Kevin Lehtiniitty.

The company’s pitch is built around a practical friction in cross-border payments: linking digital dollars to local financial infrastructure takes more than a fast settlement network. It also requires provider relationships, local expertise, compliance processes and operational support. Lehtiniitty’s career has taken him through several parts of that chain, from stablecoin issuance to fiat payment rails, and those experiences inform Borderless.xyz’s focus on connectivity and service after an integration goes live.
One connection to local payment providers
Borderless.xyz offers payment companies one API that connects them to 19 licensed local providers across 72 currencies and 132 domestic rails. Each transaction includes the conversion between stablecoin and local currency, followed by the transfer through a domestic payment system. Customers can use the platform alongside their existing wallet and compliance infrastructure.
Lehtiniitty describes the platform as three layers. The first moves funds through local providers. Operations tools sit above that layer, including rail monitoring, requests for information case management and automated reconciliation. These tools are meant to help customers add providers without having to expand their own teams at the same pace. The third layer uses transaction activity across the network to give customers a view of the rates they pay in different corridors.
That structure reflects a wider challenge for payment companies: access to a new market can bring a new set of day-to-day demands. A connection may be technically complete while teams still need to monitor service, resolve payment questions and match transactions across systems. Lehtiniitty argues that handling this operational work is part of what makes it possible for customers to expand their reach through configuration changes rather than building a new integration for every market.
Compliance must keep pace with settlement
One of the company’s recent milestones is a pilot announced with Mastercard in August. Mastercard Crypto Credential is intended to establish a shared standard and governance framework for how institutions recognize one another on digital asset payments. Lehtiniitty says the problem it addresses is a repeated compliance check: a receiving institution may redo customer verification already completed by the sending institution because it has no way to rely on that earlier work.
The result can be a mismatch between the speed of the transfer and the time required to clear it. Funds may arrive in seconds, then wait while institutions establish trust and repeat checks. The pilot is designed to run a common standard across the Borderless.xyz network, so compliance information can accompany a payment as it moves between providers. The broader challenge, as Lehtiniitty frames it, is coordination between institutions as much as technology.
Borderless.xyz says it has built the first payments network for stablecoins and describes its current coverage as the broadest available. It reports 19 licensed providers serving 113 countries, 72 currencies and 132 local rails. Lehtiniitty says customers have largely driven expansion by requesting access to additional markets. Each provider brings local expertise and its own licences, allowing the network to add coverage without requiring customers to create a separate provider connection themselves.
He points to customer use as another measure of progress: some of the largest institutions moving stablecoins use the network for parts of their payout and collection operations and continue adding markets. The company’s operating model depends on those customers being able to extend an existing setup across borders. Whether that promise holds in practice rests on provider performance, local service and the tools supporting each payment after launch.
Experience at the boundary between stablecoins and banks
Lehtiniitty has worked on stablecoins for more than a decade. He helped launch TrueUSD, which he describes as the first fully reserved US dollar stablecoin. He says its reserve framework held cash and equivalents with a qualified custodian rather than on a company balance sheet, with audits of the reserves. His focus on payments grew from watching what happened when a dollar held on a blockchain needed to become dollars in a bank account.
He later became chief product officer at Prime Trust, where he built US fiat rails for exchanges including Binance US and Kraken. He was also technical co-founder of Fortress. Across those roles, he says, he saw different parts of the same problem: reserve trust at the issuance stage, the difficulty of building payment rails, and the friction customers face when a middleman stands between them and the provider responsible for moving their money.
Borderless.xyz’s model is meant to give customers direct contracts and relationships with the providers handling funds, while the company supplies connectivity, operational visibility and back-office tools. That choice puts emphasis on clear responsibility when a payment stalls or a compliance issue arises. It also means local providers remain central to the service customers experience.
Local instant payments, slower cross-border transfers
Lehtiniitty spent more than 200 days travelling last year, reflecting his view that payments are local and require direct understanding of how each market works. In June, he met with providers in Mexico City and discussed how payouts reach recipients, including why payment behavior in Colombia can differ from Brazil. His point is that the people who operate local rails understand details that can be hard to assess from a distance.
Domestic payment speeds have changed sharply in several markets. Lehtiniitty cites PIX in Brazil, UPI in India and SPEI in Mexico as systems that let money move in seconds, including for everyday payments. Yet cross-border transfers can still take days as they pass through correspondent banks. Stablecoins offer a way to connect markets, but the local transfer at the destination remains variable. The industry’s test is whether it can join fast international settlement to dependable delivery into local accounts and wallets.
That gap between the story and the working service is one of Lehtiniitty’s main frustrations. He says announcements can describe broad market coverage while individual rails remain in beta, provider preparations are incomplete or test environments fail. Those limits may only become clear once a company has signed on and begun integrating. The cost, he says, can be months of engineering effort and lost credibility with a company’s own customers.
Expansion and the next operating challenges
Several institutions are testing their onramps and offramps on Borderless.xyz, with plans to scale, according to Lehtiniitty. He says the coming twelve months are a significant period for the company because the infrastructure it has built over two and a half years is beginning to support further growth. Latin America and Africa are its deepest areas of coverage today; Asia and the Gulf Cooperation Council region are priorities for the rest of the year.
The company is also continuing to build tools for the work that follows an integration: reconciliation, provider status monitoring and case management for requests for information. Lehtiniitty says that operational burden can stop a company from adding a second provider. The Mastercard Crypto Credential pilot is another part of the plan; Borderless.xyz intends to apply what it learns across its wider network so institutions can rely on compliance work completed earlier in a payment’s path.
Another planned resource, which Lehtiniitty calls the Benchmark, aims to become a public reference for the cost of delivering a stablecoin payment into each country. He says it is getting closer to that role each quarter, with the goal of making pricing visible before companies sign a contract. Its value will depend on whether the information becomes broad and useful enough for buyers to compare actual delivery costs across markets.
For the wider industry, Lehtiniitty identifies three open questions: clearer US market structure rules, compliance that can travel with funds, and dependable last-mile settlement. He says the GENIUS Act and MiCA have helped define expectations for compliant issuers, while broader US market structure rules remain unsettled. More than 70 countries now have instant domestic payment systems, he says, but connecting those systems is only part of the task. The practical measure will be whether providers can reliably turn fast stablecoin settlement into money recipients can use locally.
Lehtiniitty also points to a lesson from Borderless.xyz’s early product work: shipping too slowly meant losing months of customer feedback. He says the company learned more by putting products in front of the teams that had to use them and fixing the problems they found. That approach, paired with local provider relationships and operational tools, will shape whether its expanding network can turn headline coverage into payments that work consistently at volume.
The post In Profile: Kevin Lehtiniitty, CEO at Borderless.xyz appeared first on The Fintech Times.


